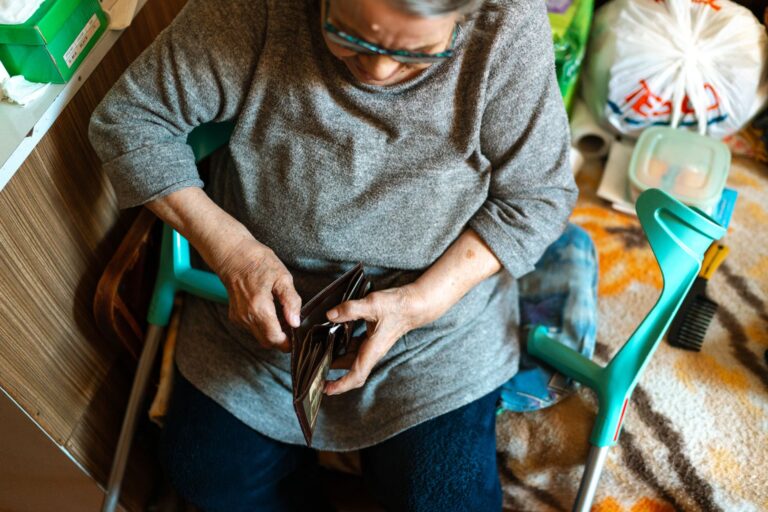
Yes, trouble managing money can be one of the earliest warning signs of dementia, and in many cases it shows up before more obvious memory problems appear. Financial tasks draw on a wide range of cognitive skills at once — attention, arithmetic, judgment, planning, and short-term memory — so when the brain begins to change, everyday activities like paying bills, balancing accounts, or understanding a bank statement often become difficult before a person forgets names or appointments. Researchers who study Alzheimer’s disease have repeatedly found that declines in financial ability can precede a formal diagnosis by several years. Consider a retired accountant who spent decades handling complex tax returns without a second thought. Family members grew concerned when she began missing utility payments, writing checks for the wrong amounts, and leaving stacks of unopened mail on the kitchen table.
A cognitive evaluation months later revealed early-stage Alzheimer’s. Her difficulty with money was not carelessness or laziness; it was an early expression of the disease affecting the parts of her brain responsible for calculation and judgment. That said, money trouble alone does not mean someone has dementia. Stress, depression, poor eyesight, medication side effects, and simple unfamiliarity with online banking can all cause similar problems. The key is noticing a change from how a person used to handle their finances, especially when it appears alongside other subtle shifts in thinking and behavior.
Medical information disclaimer: This article is for general educational purposes only and does not provide medical advice, diagnosis, or treatment. Always consult a physician or other qualified health professional about symptoms, medications, tests, or treatment decisions.
Table of Contents
- Why Is Trouble Managing Money an Early Dementia Warning Sign?
- How Financial Warning Signs Differ From Normal Aging
- What Financial Mistakes Look Like in Early Dementia
- How to Respond When You Notice Money Trouble
- Legal and Safeguarding Steps, and Their Limits
- The Role of Banks and Technology
- How Clinicians Assess Financial Capacity
- Frequently Asked Questions
Why Is Trouble Managing Money an Early Dementia Warning Sign?
Financial management is what neuropsychologists sometimes call a “cognitively demanding instrumental activity of daily living.” Unlike brushing teeth or getting dressed, paying bills and managing a budget require the brain to juggle several functions simultaneously. A person has to remember which bills are due, calculate whether there are enough funds to cover them, weigh priorities, and follow a multi-step process to completion. When the neural networks supporting these skills start to erode, money tasks are among the first to break down. The brain regions affected early in Alzheimer’s disease include areas involved in memory and, importantly, in numerical processing and executive function. This helps explain why a person might still hold a warm conversation and recognize loved ones while quietly struggling to reconcile a checkbook.
Compare it to a bridge under strain: the heaviest-loaded beams show cracks first. Financial decision-making carries a heavy cognitive load, so it often reveals stress before lighter tasks do. A frequently cited example involves adult children who discover that a parent has fallen behind on bills despite having plenty of money in the bank. The problem is not a lack of funds but a growing inability to organize and execute the steps of paying. This pattern — capable resources but failing execution — is a classic early signal that something has changed cognitively.
How Financial Warning Signs Differ From Normal Aging
It is normal for financial habits to shift with age. Older adults may take longer to do math in their heads, occasionally forget a single payment, or feel overwhelmed by a confusing new banking app. These lapses, on their own, are not cause for alarm. The distinction that matters is between an occasional slip and a persistent, worsening decline in abilities the person once handled with ease. With dementia, the trouble tends to be progressive and out of character. A person who always paid bills on time now misses them repeatedly. Someone who was financially savvy struggles to understand what a bill even represents. There may be unusual purchases, repeated payments for the same service, or difficulty counting change at a store.
These are not one-time mistakes but a pattern that deepens over months. An important warning and limitation here: financial difficulty is a clue, not a diagnosis. Many treatable conditions mimic these symptoms. Depression in older adults can sap the motivation to open mail or manage accounts. Urinary tract infections can cause sudden confusion. Certain medications impair concentration. Vision loss can make statements unreadable. Jumping to a dementia conclusion without a medical evaluation can cause unnecessary fear and may overlook a reversible cause.
What Financial Mistakes Look Like in Early Dementia
The specific errors people make can be surprisingly telling. Some individuals begin making arithmetic mistakes when calculating a tip or verifying a receipt. Others lose track of routine expenses, forgetting whether the rent or mortgage has been paid. A once-frugal person may become uncharacteristically impulsive with purchases, while another may become fearful and hide cash around the house because they no longer trust their own record-keeping.
Vulnerability to scams is another prominent and dangerous sign. As judgment and reasoning decline, people become more susceptible to phone fraud, sweepstakes schemes, and high-pressure sales pitches. Consider a widower in his late seventies who wired thousands of dollars to a caller claiming to be his grandson in legal trouble — a classic “grandparent scam.” His family later learned this was one of the first outward signs of his cognitive decline, as the reasoning that would once have made him skeptical had quietly weakened. These mistakes often accumulate in the background because money is a private matter. Many older adults value their independence and are reluctant to admit difficulty, so problems can go unnoticed until a crisis, such as a disconnected utility or an overdrawn account, forces the issue into the open.
How to Respond When You Notice Money Trouble
If you observe a loved one struggling with finances, the first practical step is to approach the subject gently rather than confrontationally. Framing matters: offering to help review bills together preserves dignity far better than announcing that someone can no longer be trusted with money. The next step is to encourage a medical evaluation, which typically includes cognitive testing, a review of medications, and screening for depression and other conditions. There is a genuine tradeoff to weigh when it comes to taking over financial tasks. Stepping in too aggressively can strip a person of autonomy and self-worth, potentially accelerating feelings of helplessness.
Stepping in too slowly risks serious financial harm, including drained savings or damaged credit. A middle path — shared oversight, where the person retains involvement while a trusted family member monitors accounts — often works better than an abrupt handover in the earliest stages. Compared with waiting until a crisis, early and open planning gives families far more options. Setting up account alerts, consolidating scattered accounts, and arranging automatic payments can reduce the daily cognitive burden while a person is still able to participate in those decisions. The alternative, reacting after significant losses, is both more stressful and more expensive.
Legal and Safeguarding Steps, and Their Limits
Beyond day-to-day help, families often need to address legal protections. Establishing a durable power of attorney for finances while the person still has the capacity to understand and sign it is one of the most valuable steps a family can take. This document allows a trusted agent to manage financial affairs if the person becomes unable to do so. Waiting too long can foreclose this option, because a person must be competent to grant it. A serious warning applies here: financial exploitation of people with cognitive decline is common, and it is not always strangers who are responsible.
Family members, caregivers, and acquaintances can also take advantage. Granting broad financial authority to any single person without safeguards, such as oversight from another relative or a professional, can itself create risk. Choosing an agent carefully and building in accountability matters as much as having the document at all. There are also limits to what safeguarding can accomplish. Banks and legal instruments can slow or flag suspicious activity, but they cannot fully compensate for impaired judgment, and privacy laws can make it difficult for family members to intervene until documented authority is in place. This is precisely why acting during the early window, while planning is still possible, is so important.
The Role of Banks and Technology
Financial institutions have become more aware of cognitive decline among aging customers, and many now offer tools that can help. Some banks allow a trusted contact to be named on an account, so the institution can reach out if it notices unusual activity or signs of possible exploitation. Automatic bill pay, low-balance alerts, and spending limits on cards can act as guardrails without removing a person’s independence entirely.
For example, a family concerned about a parent’s impulsive online purchases arranged for read-only account access and set up text alerts for any transaction over a set amount. This allowed them to spot problems quickly while leaving the parent in control of routine spending. Technology of this kind cannot replace human attention, but it can buy time and reduce the chance that a single mistake spirals into a major loss.
How Clinicians Assess Financial Capacity
When cognitive concerns bring someone to a clinician, financial ability may be assessed directly. Neuropsychologists sometimes use structured tools that ask a person to perform tasks such as counting coins, understanding a bank statement, or deciding how to handle a hypothetical bill. These assessments help distinguish between someone who is simply out of practice and someone whose reasoning has genuinely declined.
Financial capacity is also understood to be task-specific rather than all-or-nothing. A person in the early stages might still manage simple cash transactions competently while being unable to handle complex tasks like investment decisions or tax filing. This is why a careful evaluation looks at particular abilities rather than issuing a blanket judgment, and why the same person may need help with some money matters while remaining fully capable of others.
Frequently Asked Questions
Does trouble with money always mean dementia?
No. Depression, medication side effects, infections, vision loss, and unfamiliarity with new banking systems can all cause similar difficulties, which is why a medical evaluation is essential.
How early can financial problems appear before a dementia diagnosis?
Research on Alzheimer’s disease suggests declines in financial ability can appear several years before a formal diagnosis, sometimes before noticeable memory loss.
What is usually the first financial sign families notice?
Often it is unpaid bills piling up despite adequate funds in the bank, reflecting difficulty organizing and completing tasks rather than a lack of money.
What legal step should families take early?
Setting up a durable power of attorney for finances while the person still has the capacity to understand and sign it is one of the most important protective steps.
Why are people with early dementia more vulnerable to scams?
Declining judgment and reasoning make it harder to recognize deception, leaving people more susceptible to phone fraud and high-pressure schemes.