Financial vulnerability before dementia diagnosis means missed payments and weaker credit that appear years before doctors diagnose dementia, a loss of memory and thinking that disrupts daily life. The National Institute on Aging review from its virtual March 17-19, 2026 summit treats this early money trouble as a caregiving issue that working families can plan for. That planning matters because care often overlaps with a job. Money slips can grow while a parent still lives alone and a son or daughter is still working full time.
Medical information disclaimer: This article is for general educational purposes only and does not provide medical advice, diagnosis, or treatment. Always consult a physician or other qualified health professional about symptoms, medications, tests, or treatment decisions.
Table of Contents
- How early do money problems appear?
- Who faces the longest risk?
- Why does this strain working caregivers?
- What can families do now?
How early do money problems appear?
Medicare beneficiaries who later received dementia diagnoses were more likely to miss bill payments as early as six years before diagnosis, according to the Johns Hopkins analysis of early financial symptoms from the Johns Hopkins Bloomberg School of Public Health. The study linked Medicare claims and credit records for 81,364 people in single-person households, including 27,302 with dementia diagnoses.
Missed credit-card payments often rose about five years before diagnosis. Late mortgage payments followed about three years before, with higher subprime-credit risk from 2.5 years before, according to the NIA summary of bill-payment difficulty from National Institute on Aging news.
Who faces the longest risk?
Time at risk is not equal. Lower-education beneficiaries showed missed payments seven years before diagnosis, compared with 2.5 years for higher-education beneficiaries. Less schooling meant a longer window for fees, missed payments, and credit harm.
Harm did not end at diagnosis. Adverse outcomes persisted at least 3.5 years after diagnosis, with lower credit scores that did not recover. The study used only Medicare claims plus credit reports, so some cases and non-credit bills like utilities, rent, or medical debt may have been missed.
Why does this strain working caregivers?
About 60% of Alzheimer's and dementia caregivers were employed in the past year, according to the Alzheimer's Association report on employed caregivers from the Alzheimer's Association. Among those caregivers, 57% arrived late, left early, or took time off, and 16% took a leave of absence.
Work time and money vigilance compete. A missed card payment may look small during a busy workweek. Repeated misses can signal that a parent needs help with bills, mail, passwords, and due dates.
What can families do now?
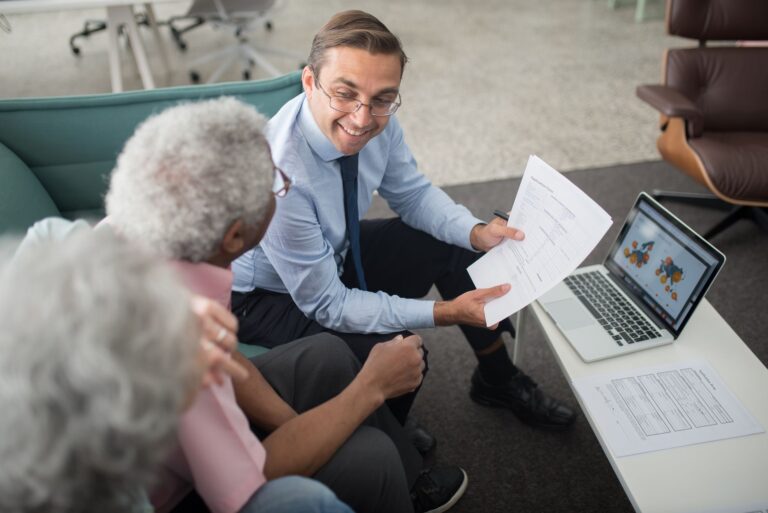
The National Institute on Aging advises families to check bank statements monthly and, as disease worsens, to take charge through legal arrangements, according to the NIA guidance for managing money problems from National Institute on Aging guidance. It prefers durable financial power of attorney arranged while the person can still consent.
- Review bank and card statements each month for late fees and new charges
- List rent or mortgage, utilities, insurance, and loan due dates in one place
- Ask the bank about alerts, autopay for fixed bills, and limits on large transfers
- Complete durable financial power of attorney while consent is still possible
You Might Also Like
- Financial Vulnerability Before Dementia Diagnosis in the 2026 NIA Report: Service Gaps That Matter to Working Dementia Caregivers
- Unpaid Dementia Care Costs in the 2026 NIA Summit Report: A Source-Checked Briefing for Working Dementia Caregivers
- Insurance Fragmentation and Dementia Costs in the 2026 NIA Report: Service Gaps That Matter to Working Dementia Caregivers