Dementia progressively damages the brain regions responsible for judgment, reasoning, and impulse control—functions essential to sound financial decision-making. People with dementia often struggle to understand complex financial information, forget recent transactions, become vulnerable to scams, or make unusually impulsive purchases that contradict their lifelong values and spending habits. Early in the disease, these changes may be subtle: a normally frugal person begins spending excessively on items they don’t need, or someone who always managed bills meticulously starts missing payments or failing to recognize fraudulent charges on their statements.
The financial impact of dementia can be devastating. Studies show that people with mild cognitive impairment or early-stage dementia lose an average of $2,100 per month to financial exploitation or poor decision-making, and losses can accelerate as the disease progresses. Beyond the monetary loss, financial mismanagement can create additional stress for caregivers, trigger family conflicts, and jeopardize the person’s long-term security and dignity. Understanding how dementia affects financial capacity is critical for families, caregivers, and the person themselves, because early recognition and intervention can prevent irreversible damage to savings, property, and credit.
Table of Contents
- WHAT COGNITIVE ABILITIES DOES DEMENTIA DAMAGE THAT AFFECT MONEY MANAGEMENT?
- HOW DOES FINANCIAL DECLINE PROGRESS AS DEMENTIA WORSENS?
- WHAT ARE THE EARLY WARNING SIGNS OF FINANCIAL DECLINE?
- HOW CAN FAMILIES PROTECT A PERSON’S FINANCES WHEN DEMENTIA IS SUSPECTED?
- WHAT ARE THE MOST COMMON FINANCIAL MISTAKES PEOPLE WITH EARLY-STAGE DEMENTIA MAKE?
- HOW DO LEGAL DOCUMENTS PROTECT FINANCIAL CAPACITY DECISIONS?
- HOW CAN YOU DETECT FINANCIAL EXPLOITATION AND RESPOND?
- Frequently Asked Questions
WHAT COGNITIVE ABILITIES DOES DEMENTIA DAMAGE THAT AFFECT MONEY MANAGEMENT?
dementia attacks the executive functions of the brain—the prefrontal cortex and related structures that handle planning, memory, attention, and judgment. Financial decision-making requires all of these skills working together: you must remember past transactions, understand current options, anticipate future consequences, and resist impulsive urges. As dementia progresses, each of these abilities deteriorates. Memory loss is often the most obvious symptom. A person may forget they already paid a bill and pay it again, or forget a purchase they just made and feel confused about a new charge on their bank statement.
Working memory—the ability to hold and manipulate information mentally—also declines, so a person might not be able to track multiple transactions at once or understand a financial document that requires them to cross-reference information from multiple places. Someone who once balanced a checkbook mentally might now be unable to do simple arithmetic or compare numbers meaningfully. Beyond memory, judgment and impulse control deteriorate. The part of the brain that says “this seems like a scam, I should verify it” or “I already own ten of these, I don’t need another” becomes less active. People with early-stage dementia often cannot weigh consequences: they may not understand that spending $500 today means less money for rent next month. Some people become unusually rigid and refuse to make any financial decisions at all; others become reckless and spend without thought.
HOW DOES FINANCIAL DECLINE PROGRESS AS DEMENTIA WORSENS?
Financial decision-making ability does not decline in a straight line; instead, it tends to drop sharply at certain thresholds as cognitive abilities cross critical tipping points. In early-stage dementia—mild cognitive impairment to early Alzheimer’s—a person can often still handle routine, familiar tasks like paying bills they’ve paid for years, but they begin to make mistakes on new or complex decisions. They might lose track of larger financial plans or investments they don’t interact with regularly. They may also become suspicious or paranoid, insisting their money was stolen when it was simply spent or moved. As dementia enters the middle stage, the decline accelerates. Many people lose the ability to recognize the consequences of their actions.
They may think they are being generous when they send money to strangers or sign documents they don’t understand, or they may feel victimized and angry when told they cannot spend money freely. A person who begins middle-stage dementia may no longer be able to recognize their own signature, understand a contract, or explain why they made a financial decision. This is the period when financial exploitation by family members, friends, or strangers often accelerates, because the person is less able to notice or report it. In late-stage dementia, most people have lost the capacity to make any financial decisions independently. At this point, financial security depends entirely on the caregiving systems that were—or were not—put in place earlier. The damage done during the middle stages becomes permanent and irreversible.
WHAT ARE THE EARLY WARNING SIGNS OF FINANCIAL DECLINE?
Family members and caregivers often notice financial warning signs before they notice cognitive ones. A sudden change in spending habits—such as frequent, large purchases of items the person doesn’t need or rarely mentioned buying—is a red flag. So is a person who becomes secretive or defensive about money or bank statements, or who claims bills were paid when they clearly were not. Some people develop an unusual focus on money: asking how much things cost, worrying about running out of money despite having adequate savings, or obsessing over small expenses. Unpaid bills and missed payments are common early indicators, especially if the person has a history of always paying on time. Late fees, warnings from creditors, or collection notices suggest the person is no longer reliably managing money, even if they claim they are.
Another warning sign is confusion about statements: the person no longer understands their checking account, cannot recognize charges, or becomes angry or frustrated when trying to read financial paperwork. Some people stop paying bills altogether because they no longer understand what bills are or why they need to pay them. A person might also become unusually susceptible to scams or investment offers. Someone who was skeptical their entire life may suddenly believe an email scam, call a phone number from a suspicious advertisement, or agree to send money to a stranger online. They may also become a target for financial exploitation because they no longer remember previous warnings or recognize manipulation. If a family member keeps asking the person for loans or “help” with money, and the person agrees even though they previously would have refused, that is a warning sign too.
HOW CAN FAMILIES PROTECT A PERSON’S FINANCES WHEN DEMENTIA IS SUSPECTED?
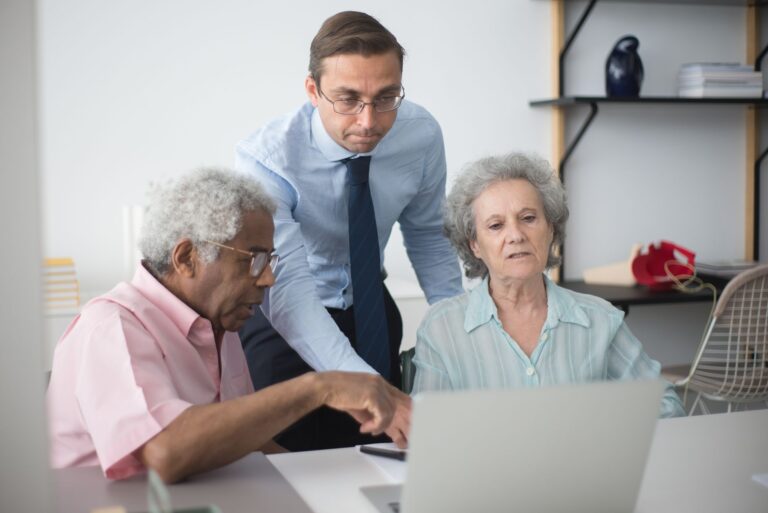
The most important step is early intervention. As soon as cognitive decline is suspected—even before a diagnosis—it is wise to have a conversation about finances and decision-making capacity. This conversation should happen when the person is lucid, willing, and can still participate meaningfully. The goal is to understand the person’s wishes and to establish legal structures that will protect their interests later. A Durable Power of Attorney for finances allows a trusted person—called the attorney-in-fact—to manage the person’s money if they become unable to do so. This must be signed while the person still has legal capacity, meaning they can understand what the document does and why they are signing it.
A healthcare power of attorney or healthcare proxy is separate and allows someone to make medical decisions. Both should be in place. A revocable living trust can also protect assets and avoid probate, though it requires planning before decline is severe. After legal structures are established, practical steps include consolidating accounts into fewer, simpler places; removing the person from being the bill-payer for mortgage, utilities, and other regular expenses; reviewing all credit cards and financial accounts monthly; and flagging suspicious activity immediately. Many banks offer alerts that notify a designated family member if large transactions occur. Some families change the mailing address for financial statements to send copies to a trusted family member who can monitor for fraud. These measures are not foolproof—scammers are sophisticated and can still manipulate an elderly person—but they create layers of protection.
WHAT ARE THE MOST COMMON FINANCIAL MISTAKES PEOPLE WITH EARLY-STAGE DEMENTIA MAKE?
Impulse spending is perhaps the most common problem. A person with early dementia might spend hundreds of dollars on items they find online or in the mail, or make repeated purchases of the same item because they forget they already bought it. Over time, impulse spending can drain significant savings. What makes this difficult for families is that the person often does not perceive their spending as excessive; from their perspective, they are simply buying what they want, as they always have. When a family member tries to stop them, the person may feel controlled or accused of being irresponsible, leading to conflict and defensiveness. Another common mistake is large financial transfers or gifts. A person in early-stage dementia may suddenly decide to give large sums to a family member, a religious organization, a charity, or a stranger they befriend online.
They may not remember the transfer or understand its permanence. If they gave the money to someone who then disappears after getting what they wanted, the person may become a victim of financial exploitation. Unlike impulse purchases, which can sometimes be returned or canceled, a large transfer of funds is often irreversible. Families sometimes discover gifts or transfers only when bank statements arrive, and by then it is too late to recover the money. A third common mistake is falling for scams that target older adults: lottery fraud, romance scams, or fake tech-support calls. A person with dementia may not recognize these scams as familiar dangers they were warned about before, or they may remember the warning but forget it applies to the current situation. They may share bank account information or Social Security numbers with callers. Losing money to a scam creates shame and self-doubt, and the person may become angry or defensive when family members try to address it.
HOW DO LEGAL DOCUMENTS PROTECT FINANCIAL CAPACITY DECISIONS?
A Durable Power of Attorney is the most important legal tool because it takes effect immediately—unlike a regular power of attorney, which expires if the person becomes incapacitated—and it survives even after the person loses capacity. A healthcare power of attorney or medical proxy is separate from financial power of attorney and handles only medical decisions. Both should be created with the help of an elder law attorney who understands your state’s requirements.
Some people also establish a conservatorship or guardianship as a backup if the person loses capacity and no valid power of attorney exists. However, conservatorship is more invasive, more expensive, and more public than power of attorney. It requires court involvement and ongoing court oversight, and the person loses many rights. If a valid power of attorney is in place, conservatorship can usually be avoided.
HOW CAN YOU DETECT FINANCIAL EXPLOITATION AND RESPOND?
Financial exploitation of seniors with dementia is common because the person’s diminished memory and judgment make them vulnerable to manipulation. Signs include unexplained withdrawals or transfers, sudden changes in will or beneficiary designations, unexpected credit card charges, an adult child or caregiver who becomes secretive about financial matters, or bills that suddenly include services the person doesn’t use. Unexplained gifts or loans to family members, caregivers, or new “friends” are also red flags, as is a sudden reversal of previous financial decisions or values.
If you suspect exploitation, contact the person’s bank or financial institution immediately to ask about recent transactions and to alert them that the person may be vulnerable. Report suspected exploitation to Adult Protective Services in your state or local law enforcement. If a power of attorney is in place, the attorney-in-fact has a legal duty to act in the person’s best interest and can pursue legal remedies. If no power of attorney exists and exploitation is serious, guardianship or conservatorship may be necessary to stop the harm, even though it is more costly and invasive.
- —
Frequently Asked Questions
At what stage of dementia does financial decision-making become impaired?
Changes often begin in the mild cognitive impairment stage, with noticeable mistakes in complex financial tasks. Most people with early-stage dementia can still handle routine, familiar money management, but they make errors on new decisions or forget recent transactions. By mid-stage dementia, most people have lost meaningful financial capacity.
Can someone with dementia still sign legal documents?
Yes, but only if they have adequate decision-making capacity at the time of signing. A lawyer should assess capacity, and the document should be created while the person is lucid. If someone with advanced dementia attempts to sign a document, it is likely invalid. Powers of attorney and trusts are most effective when created early, before significant cognitive decline.
What should I do if my parent has already lost access to their passwords?
Contact their banks and financial institutions immediately to explain the situation. Most institutions have procedures for assisting account holders with cognitive impairment or loss of memory. You can usually gain access through a power of attorney or by requesting the institution’s account access procedures for caregivers. An elder law attorney can advise on next steps if no power of attorney is in place.
How do I convince someone with dementia that they need help with money?
Use the person’s own values and history as leverage. Remind them of how important it was to them to save money, pay bills on time, or provide for their family. Frame financial help as respecting their values, not overriding their independence. Sometimes approaching the conversation when they are most lucid, or having someone they trust deliver the message, is more effective than an adversarial family member.
Can I prevent financial exploitation without power of attorney?
It is more difficult. You can alert their financial institutions, monitor accounts with their permission, offer to help with bills, and report suspected exploitation to Adult Protective Services. However, without legal authority via power of attorney or guardianship, you cannot take direct action to stop transfers or reverse transactions if the person disagrees. This is why creating legal documents early is so important.